 By Zhi Wei and team · 4 min read
01
The quick sum we all do
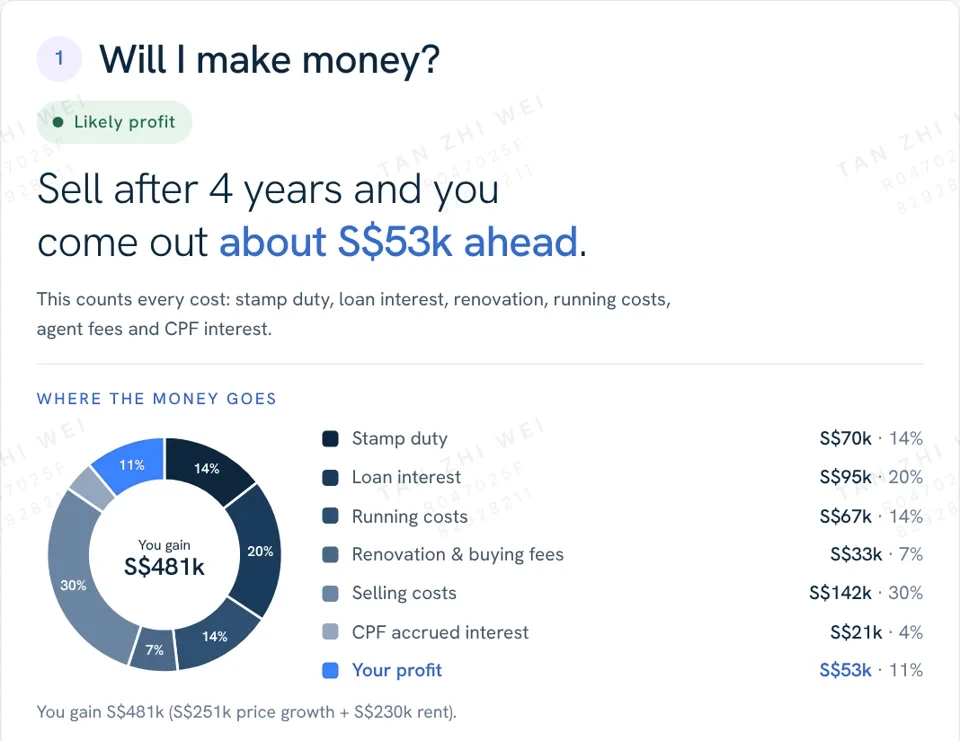
Bought at S$1.5M, now worth about S$1.74M. That's S$240k up, right? I get it. That's how most of us count it, me included. But the bank's interest, the stamp duty, the reno, the running costs, the agent fee and the CPF accrued interest you have to put back all come out of that number. Working it out yourself is a headache, so I did the heavy lifting and counted every dollar in and out.
S$238,911
Price gain on paper
S$497,661
Gains including rent
S$144,874
Real profit after costs
02
Where your gain quietly goes
Picture this. You're a Singapore Citizen and you buy a S$1.5M resale condo with a 75% loan at 2.5%. You rent it out at S$4,500 a month and sell after 5 years at 3% growth. Sounds like a good plan. By the time every cost is paid, 71% of your gains are gone.
| Item | Amount | Share of gains |
|---|---|---|
| Total gains | S$497,661 | 100% |
| Loan interest | -S$132,555 | 27% |
| Running costs | -S$82,013 | 16% |
| Buyer's Stamp Duty | -S$44,600 | 9% |
| Selling costs | -S$40,908 | 8% |
| Real profit | S$144,874 | 29% |
Renovation and CPF accrued interest are also deducted.
Same S$1.5M condo, loan at 2.5%.
What's left is a real profit of S$144,874. That's about 61% of the paper gain, or about 5.4% a year on the S$452,600 you put in. Still decent, but a lot less than the number you'd tell your friends.
03
How I work it out
For each year you could sell
Real profit = sale price − loan owed − selling costs + rent − running costs − instalments − money put in − CPF accrued interest
- Stamp duty on purchaseBuying at S$1.5M means S$44,600 in Buyer's Stamp Duty. If it's your second home, or you're a PR or foreigner, ABSD comes on top.
- Loan and CPFEvery monthly payment is part interest, part principal. Any CPF you use grows at 2.5% a year, and you pay it back when you sell. Many owners forget this one.
- Rent and running costsRent stops when the unit sits empty. MCST, property tax, insurance and leasing fees come off every year.
- Selling costsAgent commission plus GST, and legal fees. Sell within 4 years and SSD is 16%, 12%, 8% or 4% for years 1 to 4.
- Breakeven and returnYour breakeven price is what you need to sell at just to get your money back. The yearly return is an internal rate of return.
Good news: the principal you pay down isn't a cost. You get it back when you sell. Only the interest is gone for good.
04
Selling early hurts the most
Say something comes up and you sell at the end of year 1. Seller's Stamp Duty alone is 16%, or S$247,200. You'd end up S$312,718 behind. At 2.5%, your profit only turns positive in year 4 at S$21,746, then climbs to S$144,874 in year 5.
S$1.5M condo, 75% loan, rented at S$4,500 a month.
| Sell at end of | SSD | Real profit | Yearly return |
|---|---|---|---|
| Year 1 | 16% | -S$312,718 | -69.1% |
| Year 2 | 12% | -S$206,825 | -25.6% |
| Year 3 | 8% | -S$95,411 | -7.3% |
| Year 4 | 4% | S$21,746 | 1.1% |
| Year 5 | None | S$144,874 | 5.3% |
Loan at 2.5%. SSD bands for purchases from 4 July 2025.
In year 1, you'd need to sell at S$1,927,202 just to get your money back. By year 5, that bar drops to S$1,590,808.
Lines cross between year 3 and year 4.
05
When your loan rate goes up
We all hope rates stay low. But every extra point adds about S$600 to S$650 to your monthly instalment, and roughly S$55,000 of interest over five years. Even at 2.5%, the rented condo still costs you about S$1,500 a month out of pocket in year 1.
S$144,874
Year 5 profit at 2.5%
S$34,890
Year 5 profit at 4.5%
06
How much growth you need just to break even
What if prices stay flat? You'd lose S$88,828 over five years, even with rent coming in. At 1% growth, it's still a S$13,981 loss. So you need a little over 1% a year just to break even by year 5.
Loan at 2.5%, rented at S$4,500 a month.
07
What if you live in it?
If it's your own home, the question changes. On cash alone, a S$650,000 HDB flat is S$62,620 behind and the S$1.5M condo is S$71,613 behind after 5 years. But you'd have paid rent somewhere else. Count the rent you saved, and both turn positive.
S$129,380
HDB profit, rent saved counted
S$198,387
Condo profit, rent saved counted
Only count rent saved if you'd really be paying that rent otherwise. Be honest with yourself here.
08
How I checked the numbers
I checked each rule against IRAS, MAS, MND and CPF in October 2026, then ran every scenario through the same code the calculator uses. This version also fixed how Seller's Stamp Duty counts anniversaries and new launch booking dates.
Key takeaways
- Costs took back 71% of the gains. The paper gain was S$238,911, but the real profit was S$144,874.
- Loan interest was the biggest cost, at S$132,555 over 5 years.
- Selling in year 1 meant S$247,200 in Seller's Stamp Duty. Even year 4 still cost S$67,531.
- Two extra rate points cut your year 5 profit from S$144,874 to S$34,890.
What the tool does not do
- Seller's Stamp Duty uses the rates for a purchase made today. Homes bought before 4 July 2025 have lower rates.
- Rates, rent and costs stay flat, and growth is the same every year. Real life is bumpier than that.
- It doesn't model TDSR or MSR, property tax bands, or what nearby units sold for. That's where I come in.
FAQs
Does the calculator count CPF accrued interest?
Yes. CPF you use grows at 2.5% a year, worked out monthly and added yearly. On S$150,000, that's S$19,711 after 5 years, and the calculator takes it off your profit.
Is mortgage principal counted as a cost?
No. The principal you repay lowers what you still owe when you sell, so you get it back. Only the interest is a real cost.
What Seller's Stamp Duty rates does it use?
For private property bought today, selling at the end of year 1 means 16%, year 2 is 12%, year 3 is 8% and year 4 is 4%. From year 5, there's none.
Can I use it for an HDB flat?
Yes. Choose HDB flat. It uses a 75% loan limit and no SSD, and in rent-out mode rent only starts from year 6.
Sources (6)
- IRAS: Seller's Stamp Duty for residential property
- IRAS: Stamp duty rates
- MOF: Buyer's Stamp Duty rates raised for higher-value properties
- MAS: Macroprudential policies in Singapore
- MND: Measures to cool the HDB resale market (HDB loan limit 75%)
- CPF Board: Using CPF for housing
For education and illustration only. Figures depend on the inputs and the rules in force at the time of writing, and property values can fall as well as rise. This is not financial advice.